
Free in-home measure and quote - PGT, CGI and CWS impact lines compared on your actual openings, style by style
Sliding glass doors
Impact garage doorsPGTCGI
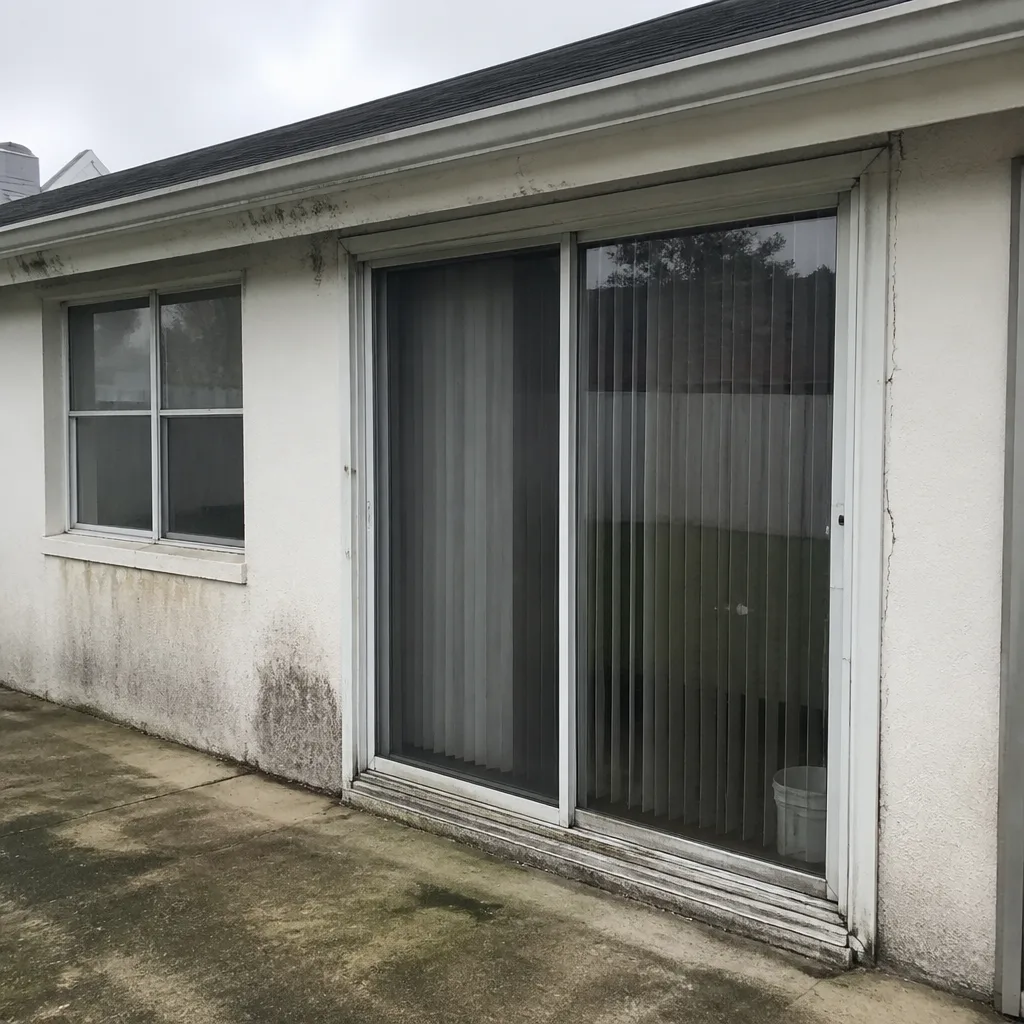 Before
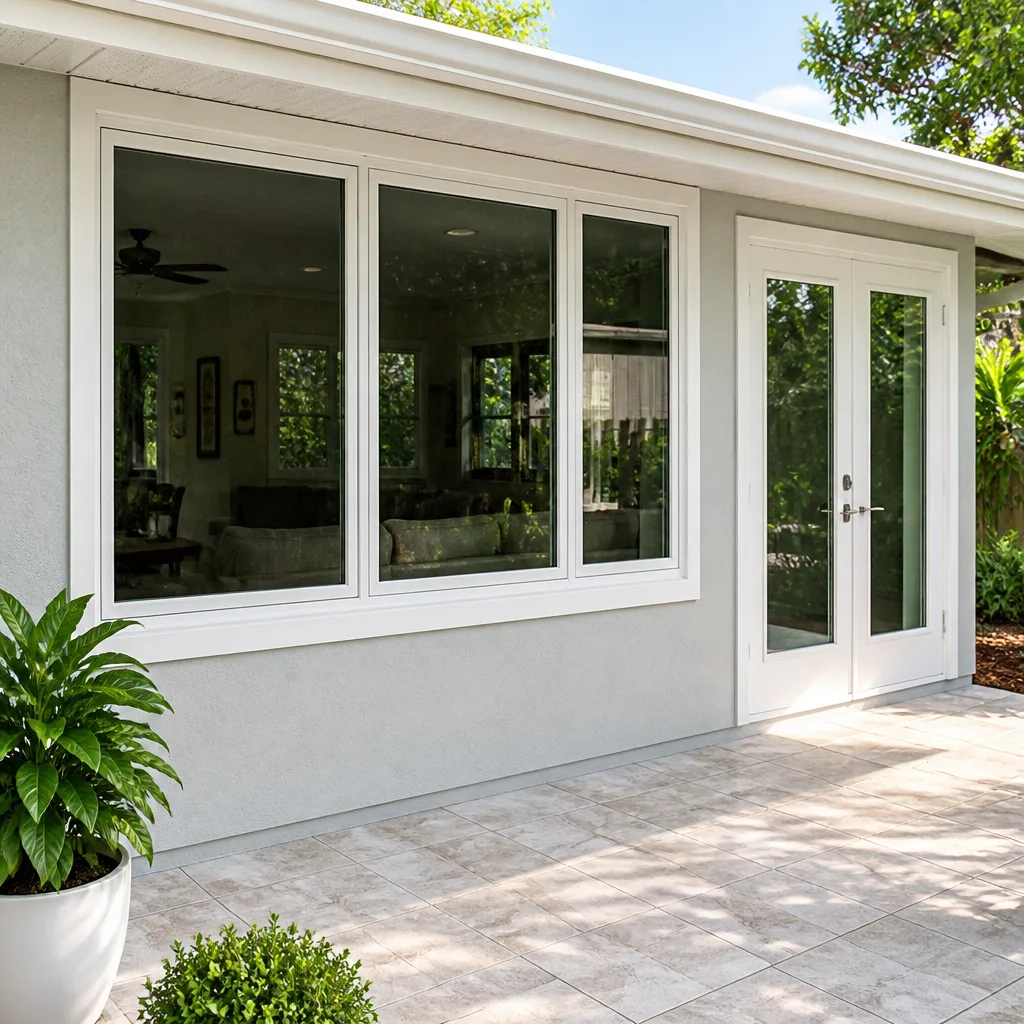 After
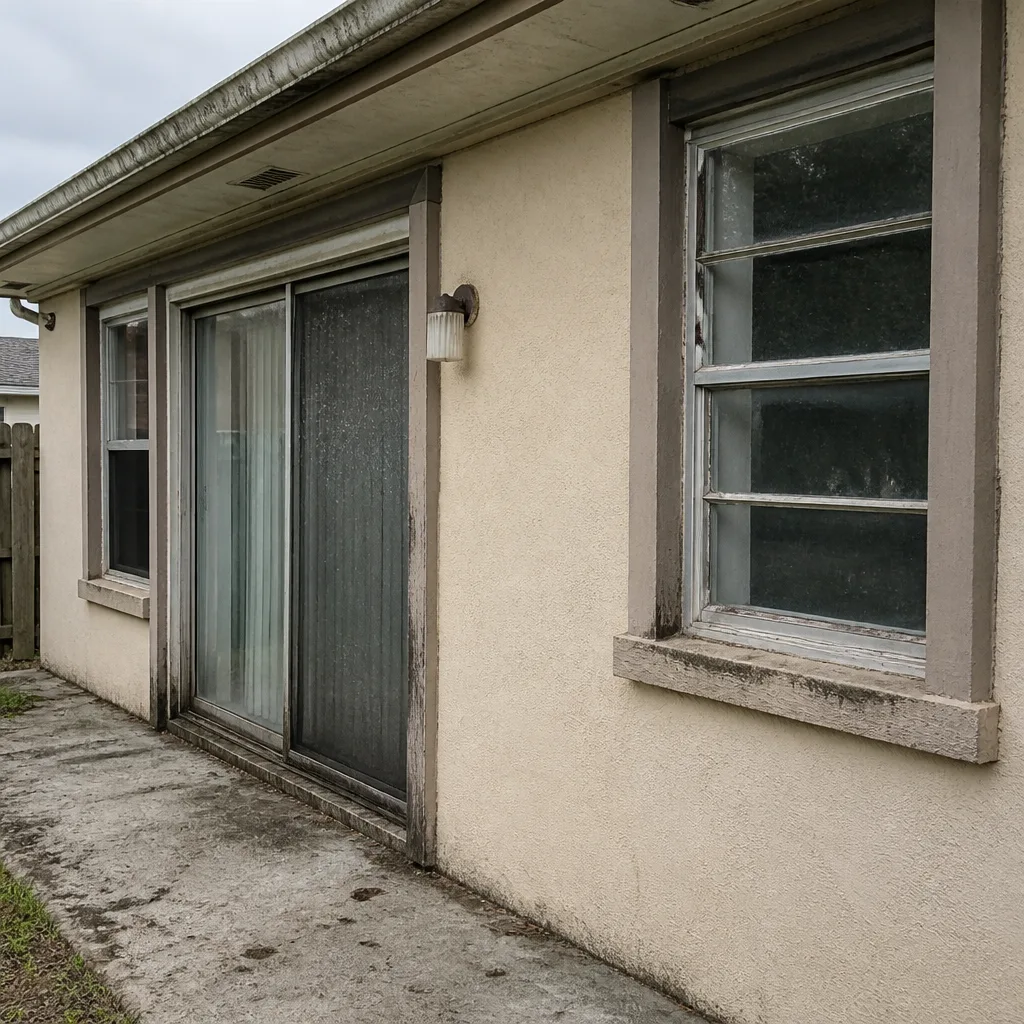 Before
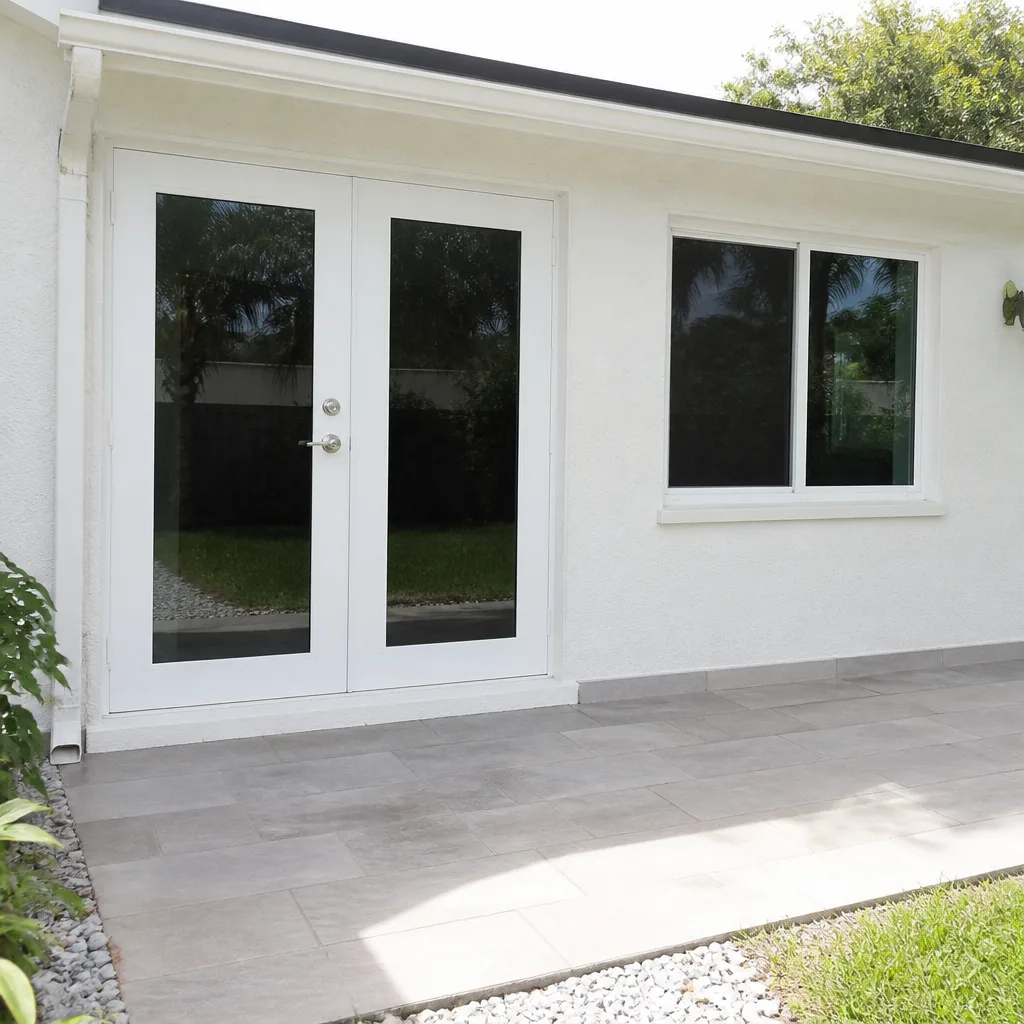 After
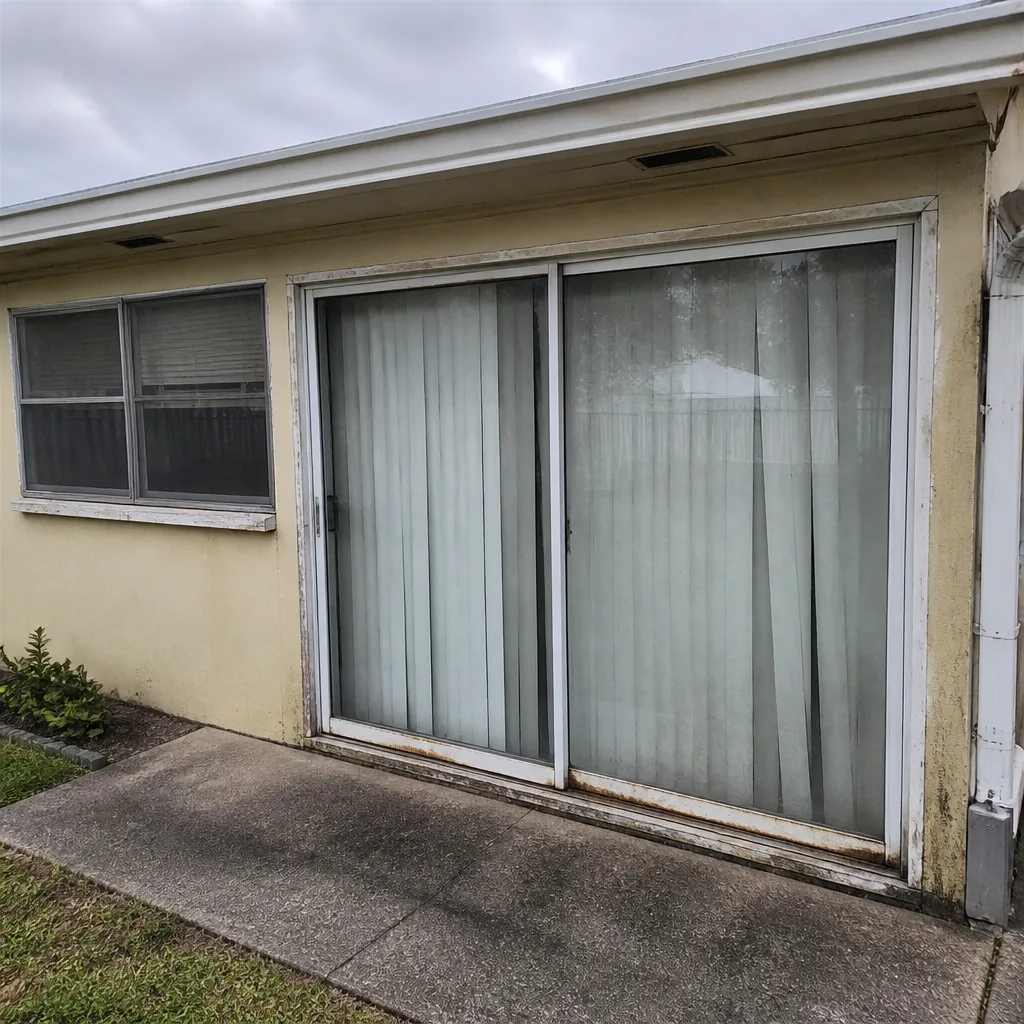 Before
 After
Do impact windows lower insurance in Greenacres, FL? Yes, often by 20-45% on the windstorm portion of your premium.
Impact windows lower insurance in Greenacres because they remove the single largest windstorm risk your insurer prices into the policy: the opening that lets pressurized wind inside the house. A rated impact unit, properly installed and documented, shifts your home from “unprotected opening” to “protected opening” in the insurer’s underwriting model. That reclassification triggers the windstorm mitigation discount most Florida carriers apply, and in Palm Beach County the windstorm line is frequently the most expensive part of the bill. Call (754) 339-0784 if you want a straight answer on your specific situation.
What your insurer actually looks at
Florida carriers don’t give a blanket discount for “impact windows.” They run your home through a windstorm mitigation inspection and score each opening separately. A window only counts as protected if it carries a Florida Product Approval rating for the design wind speed in your area, and if it was installed by someone who did the work to code. This is where Greenacres gets particular. The city sits in Palm Beach County’s wind-borne debris region but outside Miami-Dade and Broward’s High Velocity Hurricane Zone. That means your windows need Florida Product Approval at Palm Beach County design wind speeds, typically 140 mph or higher, not the separate HVHZ certification used farther south. An impact window with the wrong approval rating for this region does nothing for your premium. We see homeowners every month who paid for impact glass and have an inspection report that gives them zero credit, because the product rating and the installation paperwork don’t line up.
Dale Kessler has been reading these inspection reports long enough to know exactly where they fall apart. A missing product approval sticker, an opening measured as unprotected because the frame wasn’t set true, a permit that was never closed out. Any one of those wipes out the discount. The window itself matters, but so does every piece of paper behind it.
What the discount looks like in real numbers
The range we hear from Greenacres homeowners after a full-opening impact replacement is typically 20-45% off the windstorm portion of the premium, not the total bill. Windstorm coverage is often a third to a half of a Palm Beach County policy, so the drop on the full annual premium usually lands somewhere in the low-to-mid hundreds of dollars per year. It is meaningful money, but it’s not a premium that vanishes.
| Coverage line | Typical impact after full retrofit | What drives the number |
|---|---|---|
| Windstorm / hurricane portion | 20-45% lower | All openings rated and documented; no unprotected jalousie or single-pane left |
| Full annual premium | 10-20% lower in most cases | Wind line discount spread across the total policy cost |
| Homes with original jalousie windows | Often uninsurable at renewal | Carriers declining renewals on unprotected openings rather than pricing them |
One thing worth saying plainly: the insurance benefit is real, but it is not the only reason to do the work. The same windows that lower your wind premium also end the drafts, the fogged glass, and the aluminum frames that sweat through every humid August. If the insurance discount is what gets you to the decision, fine. The windows themselves will carry their weight long after the premium check clears.
Why Greenacres homes are different on this
Greenacres was built fast in the 1960s and 1970s, block-on-block, modest single-family homes and older rental buildings. A huge share still have the original aluminum jalousie or single-pane windows that predate Florida’s post-Hurricane Andrew code overhaul by thirty years. Those louvered glass strips offer no hurricane protection and about as much energy efficiency as an open vent. Florida insurers have been declining renewals on homes with jalousie windows at rates we have never seen before. The wind mitigation discount simply does not exist for those openings, because there is nothing to credit.
Full-opening impact replacements are the norm here, not a repair line. You’re not resealing a frame that has already twisted from thirty humid summers and UV that never lets up. You’re pulling the old aluminum out of the block and setting a rated unit that will pass inspection with the approval number legible on the glass. That is the job we do most often in this city, and it’s the one where Dale’s founding rule gets tested on every opening: if the pane is not true, the job is not done.
Common scenarios we walk through with homeowners
These are the situations we hear in living rooms across Greenacres, and how we typically answer them.
- “My insurer sent a nonrenewal letter because of my jalousie windows.” We hear this at least once a week now. The fix is a full jalousie-to-impact conversion, not a patch. A new impact window in a properly sized opening, with the Florida Product Approval documented and the permit closed, gives the insurer something to inspect and credit. We have done enough of these to know what the inspector will ask for before they arrive.
- “I already have impact windows but my premium didn’t drop.” This is almost always a documentation problem. The product approval sticker is missing, the installer never registered the warranty, or the permit was left open. We re-inspect the openings, get the paperwork right, and register both manufacturer warranty layers in writing before our truck leaves the driveway. That paper trail is what gets the discount actually applied.
- “My windows are single-pane aluminum but not jalousie. Do I still get a discount?” A properly rated impact retrofit replaces the opening. Whether the discount kicks in depends on the product rating, the install, and the paperwork. The old single-pane unit gets you no credit. The new impact unit, done right, gets you the full protected-opening classification. We quote it line by line so you see what you’re buying before any work starts.
We don’t sell the discount as a guarantee. Insurers set their own underwriting rules and those change. What we can guarantee, and what we put in writing, is that the installation is done to the standard that earns the classification. The Done Right Promise and The Keystone Standard cover the work itself: both warranty layers registered in writing, durations stated, no paperwork fights and no arguing if something isn’t right.
Is an impact window worth it if you’re not sure you’ll stay in the house?
For the homeowner who has been in the same Greenacres block house for twenty or thirty years and intends to stay, the math tends to work out over time. Wind premium savings, lower cooling bills, and not having to fight a fogged seal every few years. If you’re selling in two years, the insurance savings won’t recoup the install cost, but the house will be easier to insure and easier to sell in a market where buyers are getting the same nonrenewal letters. We lay both cases out honestly because a square deal means telling you when the numbers don’t pencil as well as when they do.
Our point of view on this comes from doing the work here since 2008, through Dale’s hands and the crews he has trained from apprenticeship. We hire local, we live here, and we answer the phone when you call. If a window is worth installing in Greenacres, it is worth installing the way a building inspector would want it done the first time. That’s the whole job.
FAQs
A full-opening impact window replacement in Greenacres typically runs $800-$1,600 per opening depending on window size, frame material, and the condition of the concrete block opening. A whole-home jalousie-to-impact conversion on a 1960s-70s Greenacres house usually lands in the $12,000-$25,000 range. Call (754) 339-0784 for a line-by-line quote on your openings. Estimates are free and the price we quote is the price on the bill.
Yes, your insurer will require a windstorm mitigation inspection document and proof that the installed units carry the correct Florida Product Approval rating for Palm Beach County’s wind zone. We register both manufacturer warranty layers in writing and make sure the approval documentation is complete before we finish the job. Call (754) 339-0784 if you have a renewal deadline coming and need the work scheduled quickly.
Most homes in Greenacres are completed in one or two days on-site for a full opening replacement, depending on the number of windows and what we find when the old frames come out of the block. We protect the work area, haul away the old aluminum, and leave the openings sealed and finished before we pull out of the driveway. Call (754) 339-0784 and we’ll give you a straight time estimate based on your house.
We keep our Greenacres schedule tight and can usually get a crew out the same week for a full opening count and quote, with installation following quickly once the windows arrive. If you’re facing a nonrenewal deadline, tell us when you call and we’ll do everything we can to beat the clock. The number is (754) 339-0784.
If you’d rather have it looked at
If you’re tired of guessing what your insurer will accept, TruePane Windows & Doors offers a no-pressure assessment in Greenacres. We’ll check your openings, tell you whether impact replacement makes sense for your house and your policy, and quote it honestly. Call (754) 339-0784 and a live person will answer.
Written by Dale Kessler, Owner, TruePane Windows & Doors at TruePane Windows & Doors, serving Greenacres, FL.
Six Reasons Homeowners Choose TruePane Windows & Doors
Impact systems engineered to design pressures up to +/-100, matched to your wind zone - your openings hold when the storm arrives.
Low-E insulated impact glass from our manufacturer lines commonly cuts monthly cooling bills 20-30%.
Laminated impact glass shuts out up to 40% of outside noise - traffic, neighbors, weather.
Monitoring services run $30-90 a month. Laminated impact glass resists forced entry around the clock, with no subscription.
Florida homeowners average around 25% savings on the windstorm portion of their policy after protecting every opening - some homes qualify for more.
A full impact package upgrades curb appeal, buyer confidence and appraised value in one project.